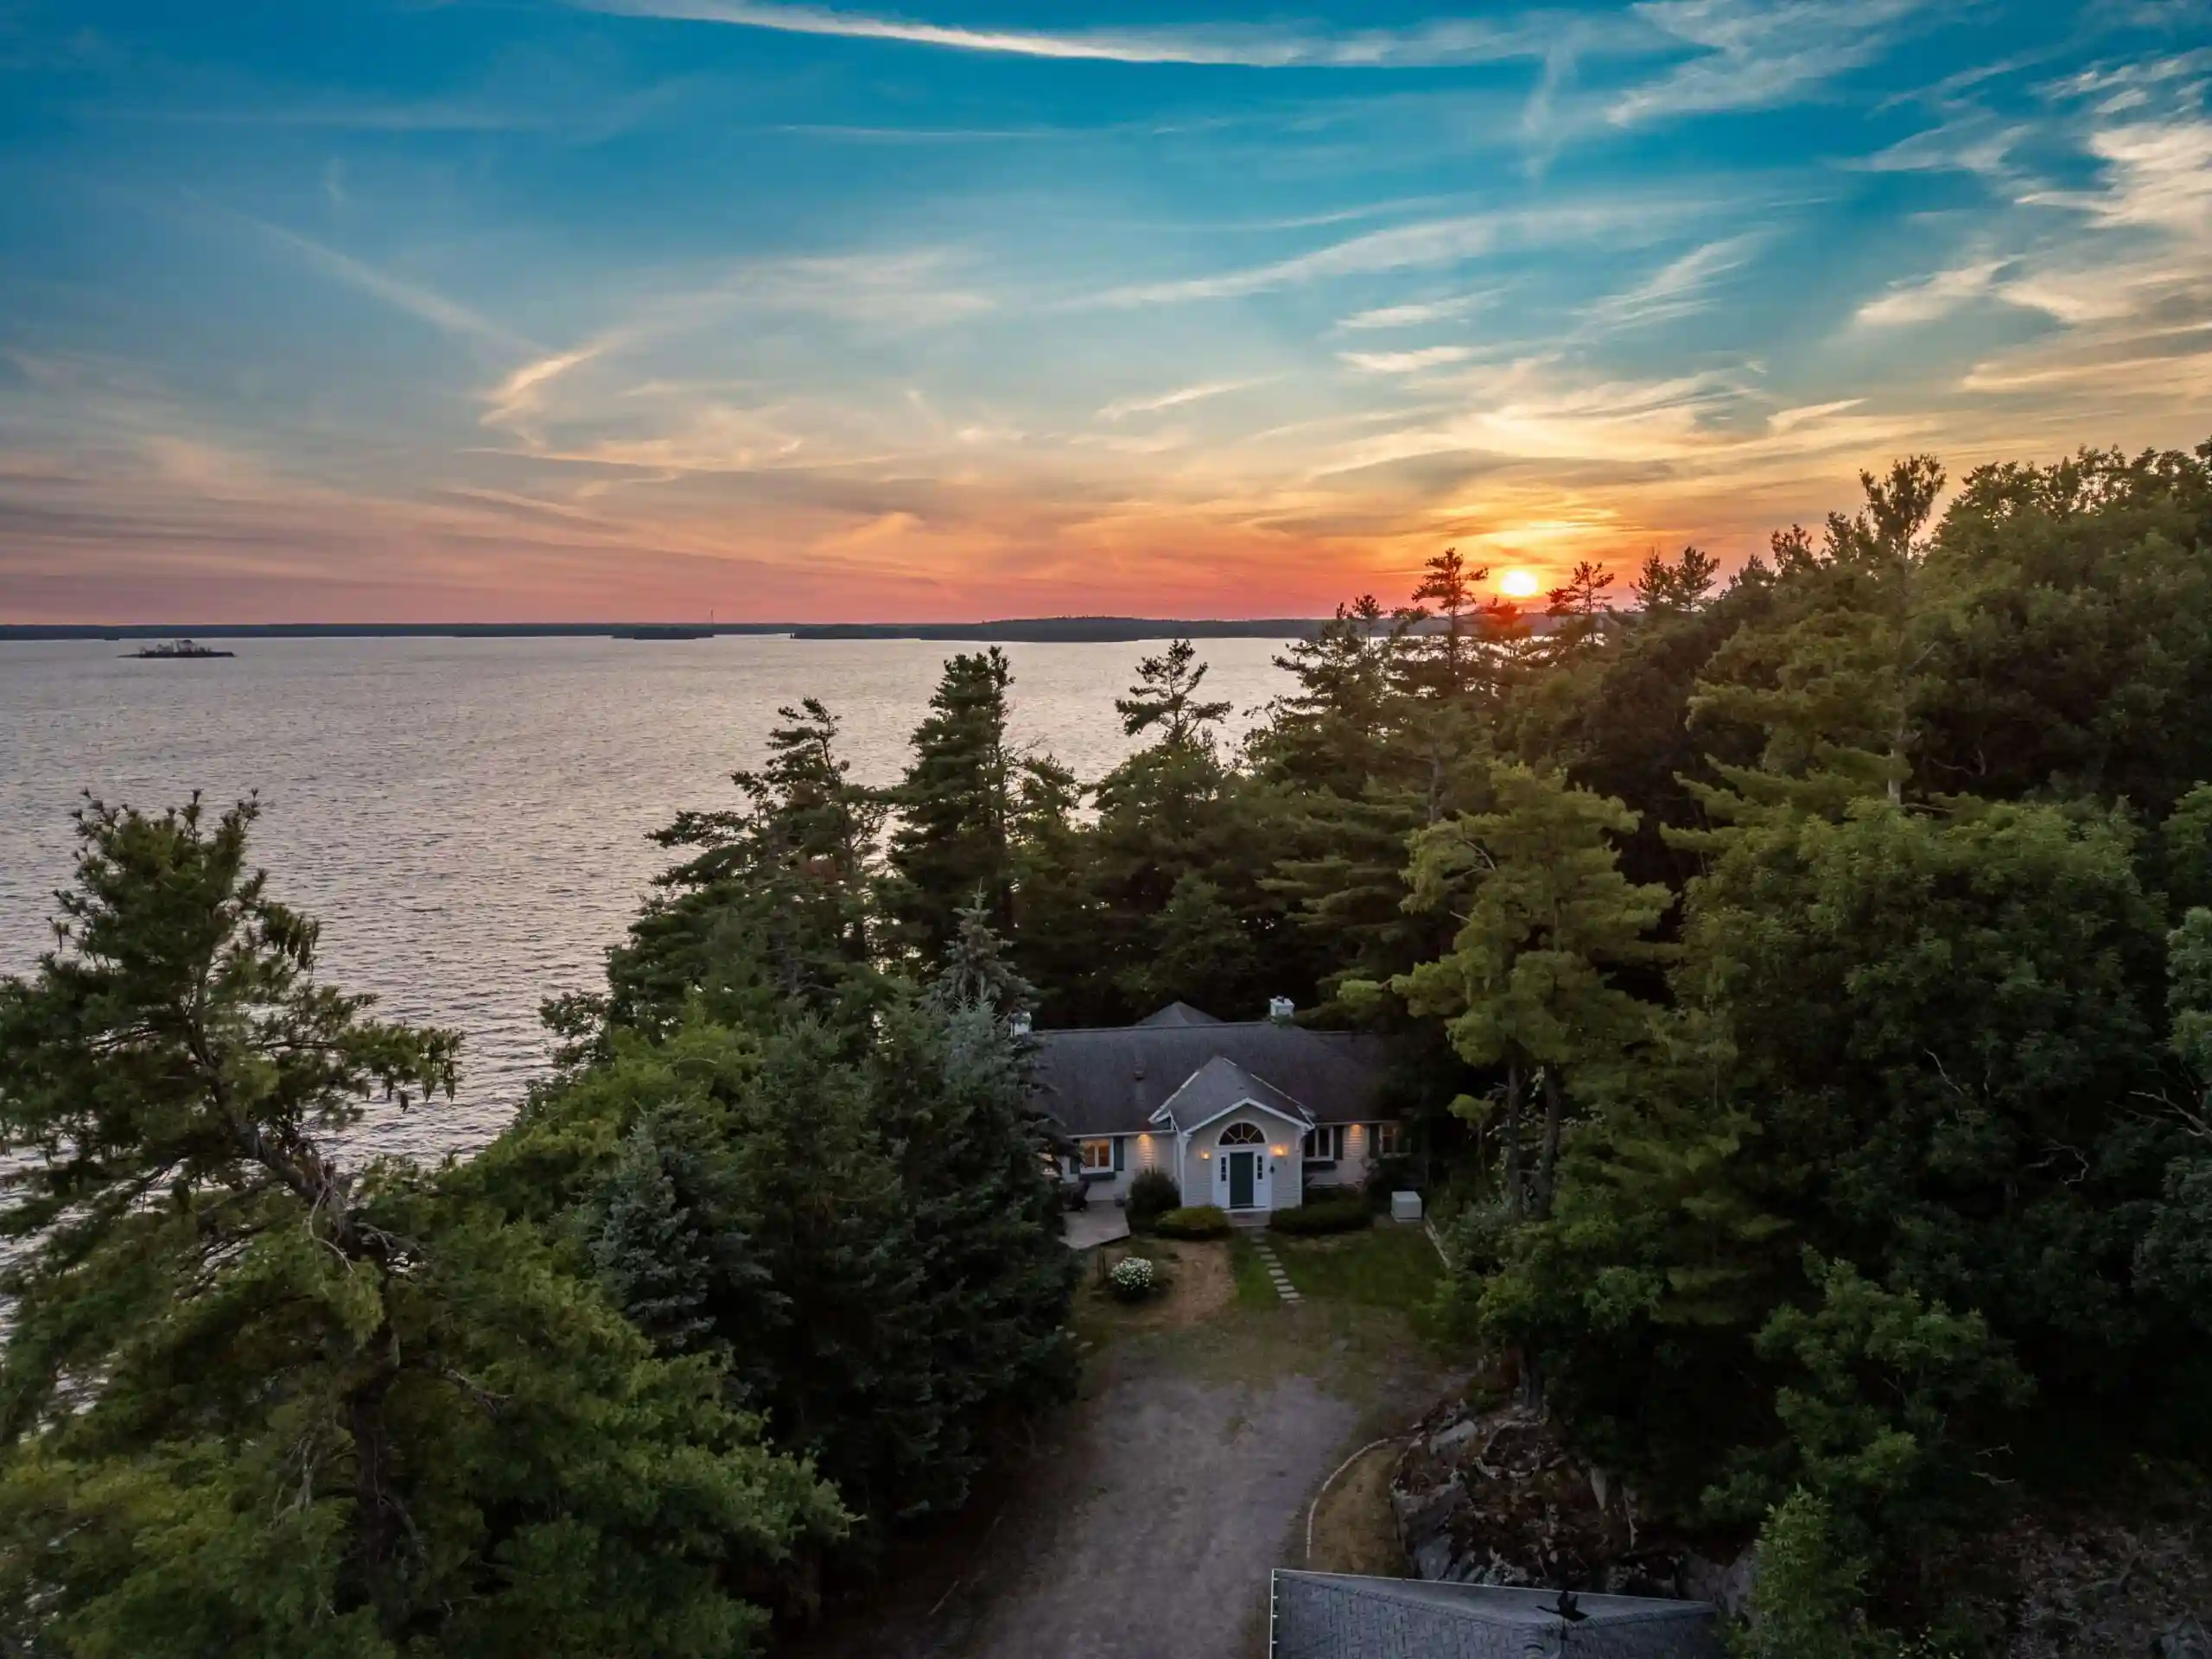
Becoming a first-time cottage buyer in Ontario is an exciting milestone, but recreational property transactions involve financing rules, zoning considerations, and inspection requirements that differ significantly from urban home purchases. This guide covers what to expect, how to prepare, and where to get the right support so your first cottage experience is grounded, not stressful.
What Should a First-Time Cottage Buyer Ontario Know Before Starting Their Search?
Ontario cottage country stretches from Muskoka and the Kawarthas to the Haliburton Highlands, Prince Edward County, and beyond. Each region carries its own character, pricing dynamics, and regulatory environment. As a first-time cottage buyer, understanding the landscape before you begin viewing properties is one of the most important steps you can take.
The Ontario cottage market has matured significantly over the past decade. Increased demand from Toronto-area buyers, a limited supply of quality waterfront properties, and evolving short-term rental regulations have created a market that rewards preparation. A buyer who walks into a cottage purchase without a clear understanding of due diligence requirements, financing constraints, and property classifications risks costly surprises after closing.
Before you start browsing listings, review our guide to buying a cottage in Ontario, a practical primer that covers the foundational decisions every first-time buyer needs to make before booking a single showing.
CV Real Estate works closely with first-time cottage buyers to build the knowledge they need before a single viewing. Book a buying call to learn how we structure buyer consultations for Ontario recreational property.
How Should a First-Time Cottage Buyer Build a Realistic Budget?
Budget planning for a first cottage purchase requires more than identifying a maximum purchase price. The all-in cost of owning a recreational property in Ontario encompasses several categories that many first-time buyers do not anticipate until they are already under contract.
Purchase Costs
Ontario Land Transfer Tax applies to all property transfers. Unlike a primary residence purchase, first-time cottage buyers do not qualify for the first-time homebuyer Land Transfer Tax rebate. That program applies to principal residences only, and a recreational property purchase is ineligible regardless of whether it is your first transaction.
Legal fees for a waterfront transaction are typically higher than a standard residential purchase due to the added complexity of reviewing permits, easements, and shoreline documentation. Our breakdown of cottage closing costs outlines what buyers should budget at each stage.
Inspection costs should include a general building inspection, a licensed septic assessment, well water testing, and a structural review of any docks or boathouses. These are not optional line items. Budget $1,500 to $3,000 or more for thorough coverage.
Survey costs may apply if the property boundaries are not clearly documented. This is common with older waterfront parcels where historical surveys may predate modern boundary standards.
Ongoing Ownership Costs
Property taxes for Ontario recreational properties are assessed annually by MPAC based on current market value. On a $1.5 million waterfront property, annual property taxes typically range from $8,000 to $14,000 or more depending on the specific Muskoka municipality. Budget for this as a fixed annual obligation before calculating your total affordability.
Maintenance costs for a cottage typically run higher than for a comparable urban home due to seasonal systems, dock upkeep, road maintenance contributions, and significant weather exposure. A reasonable baseline is 1% to 2% of property value per year for routine maintenance and capital reserves.
Insurance for a recreational property in Ontario is underwritten differently than standard home insurance. Vacancy clauses, seasonal occupancy designations, and proximity to water all affect coverage terms and annual premiums. Budget $2,500 to $6,000 per year for a typical Muskoka-area property.
The Financial Consumer Agency of Canada offers practical resources on budgeting for major property purchases that first-time buyers may find useful when stress-testing their financial readiness.
How Does Recreational Property Financing Work for a First-Time Cottage Buyer?
One of the most common surprises for a first-time cottage buyer in Ontario is discovering that mortgage rules for recreational properties are materially stricter than for principal residences. Understanding these rules before you begin your active search ensures you enter the market knowing your actual purchasing power.
CMHC mortgage insurance is not available for recreational or investment properties. You must qualify under conventional financing terms, which typically requires a minimum 20% down payment. There is no insured mortgage pathway for a cottage purchase, regardless of your credit profile.
Properties classified as seasonal or with limited road access may require a 25% to 35% down payment and may only be financeable through specialty lenders. Our guide to cottage mortgage options walks through how lenders evaluate different property and access classifications.
Your primary residence mortgage, if you have one, will factor into your debt service calculations when qualifying for a cottage mortgage. Lenders assess total debt obligations across both properties, which can meaningfully affect the cottage purchase price you qualify for.
Short-term rental income is not universally counted toward mortgage qualification by all lenders, and some municipalities across Muskoka including Gravenhurst, Huntsville, and Dysart have introduced or are actively adjusting licensing requirements and zoning restrictions on short-term rental activity. Confirm the regulatory status of your target municipality before building a financial plan that depends on rental income.
Speak with a mortgage broker who has direct experience with Ontario recreational property financing before you begin your active search. Knowing your true purchasing power before you start viewing properties shapes every decision you make from that point forward.
Our team at CV Real Estate can connect you with financing professionals who specialize in Ontario cottage property as part of our buyer advisory process.
Which Ontario Cottage Region Is Right for a First-Time Buyer?
Ontario offers a remarkable range of cottage destinations, each with distinct market dynamics, price points, and lifestyle considerations. As a first-time cottage buyer, identifying the right region for your priorities is as important as finding the right property.
- Muskoka: Muskoka is Ontario’s most established and prestigious cottage market. Lakes like Muskoka, Rosseau, and Joseph command significant premiums, with premium properties regularly trading above $3 million. The region offers strong long-term property value, excellent boating, and year-round accessibility in many areas. First-time buyers with budget constraints may find better value on interior Muskoka lakes or properties with older structures that offer renovation potential.Explore the Muskoka region guide for a breakdown of lakes, price ranges, and access characteristics.
- Haliburton Highlands: Haliburton offers a quieter, more affordable alternative to Muskoka. The region features hundreds of lakes within a two-to-three-hour drive from Toronto and consistently delivers better value per frontage foot than comparable Muskoka properties. STR bylaws and zoning designations in Haliburton County differ from Muskoka, so buyers with rental income goals should review local regulations before committing to a property.See the Haliburton community guide for a detailed overview of the area.
- Kawarthas: The Kawarthas, including Kawartha Lakes, Chemong, and Stony Lake, are popular with buyers who want a cottage within two hours of Toronto. The Trent-Severn Waterway connects dozens of lakes and adds significant boating appeal for buyers who value connected water travel. Pricing is generally more accessible than Muskoka while still offering quality waterfront experiences.Our comparison of Muskoka vs. the Kawarthas helps buyers evaluate which market fits their lifestyle and budget.
- Prince Edward County: Prince Edward County is increasingly popular with buyers who value wine tourism, arts culture, and lakefront access on Lake Ontario. Properties here differ in character from the classic Northern Ontario cottage but offer genuine lifestyle appeal for the right buyer. The market has seen significant price appreciation in recent years, and inventory of quality waterfront properties remains limited.
Not sure which region fits your goals? Our guide to best cottage locations breaks down each Ontario cottage market with a practical buyer perspective across price, access, lifestyle, and long-term value.
What Should a First-Time Cottage Buyer Look for During Property Viewings?
Property viewings for a first-time cottage buyer in Ontario should cover significantly more ground than a typical home showing. The physical condition and legal status of a waterfront property require careful attention before you allow yourself to form an emotional attachment to a specific cottage.
- Water access and frontage: The quality of the shoreline, the slope to the water, the depth at the dock, and the condition of existing dock structures all affect both daily enjoyment and future improvement costs. Confirm whether the shoreline is owned or Crown-leased before the viewing, as this changes the rights picture entirely.
- Septic system age and condition: Ask directly for the age of the system, the date of the last pump-out, and whether it has been inspected recently by a licensed inspector. An aging, undersized, or non-compliant septic system is one of the most expensive deficiencies a cottage can carry, with replacement costs ranging from $25,000 to $60,000 or more depending on soil conditions and setback constraints.
- Well and water source: Properties on private wells require active management. Ask about the depth of the well, the most recent water quality test results, whether testing has been done for bacteria, nitrates, and hardness, and the age and condition of the pressure system.
- Road access designation: Confirm whether the property is accessible year-round and whether the road is municipally maintained or privately maintained through a cottage road association. Road status directly affects financing eligibility, insurance terms, and resale value.
- Structural integrity: Muskoka-style construction with wood frame, post and beam, or log elements requires specific inspection knowledge. Always engage an inspector with demonstrated recreational property experience and walk through the full inspection report rather than relying on the summary alone.
The Ontario Real Estate Association (OREA) provides educational resources for Ontario property buyers, including guidance on standard purchase agreement conditions and property disclosures that apply to recreational property transactions.
Why Should a First-Time Cottage Buyer Work With a Specialist Advisor?
The value of working with a real estate advisor who specializes in Ontario recreational property is difficult to overstate for a first-time cottage buyer. This is not a transaction that benefits from a generalist approach. The due diligence requirements, property classifications, shoreline regulations, and financing rules that govern cottage purchases are distinct from urban residential practice.
CV Real Estate brings personalized, experienced guidance to every cottage buyer engagement. Our advisors understand regional differences between Ontario cottage markets, the due diligence requirements, waterfront transactions demand, and the patience first-time buyers need. Unlike generalist brokerages, we also operate Cottage Vacations, meaning our market knowledge is backed by real rental data, actual occupancy rates, and firsthand knowledge of STR bylaws across Muskoka municipalities. Learn more about our rental data advantage.
If you are still in the early research phase, our Try Before You Buy program allows you to rent a property through Cottage Vacations before making a purchase decision, letting you pressure-test both the property and the region with none of the financial exposure of ownership.
Reach out through CV Real Estate to arrange an initial consultation with an Ontario cottage property advisor.
What Mistakes Do First-Time Cottage Buyers Commonly Make in Ontario?
Understanding where first-time buyers commonly go wrong is one of the most practical ways to protect your investment from the start. These are not rare errors. They occur regularly among buyers who are well-prepared in most areas but underestimate the specific demands of a waterfront purchase.
- Waiving conditions under competitive pressure: In a competitive market, some buyers waive inspection and financing conditions to secure a property. On a cottage purchase, this is a significant and often irreversible risk. Waterfront properties carry a volume of potential latent defects including septic failures, unpermitted structures, and title encumbrances that can only be uncovered through proper due diligence.
- Underestimating ongoing costs: Many first-time buyers focus entirely on the purchase price and miss the full weight of annual carrying costs. Property taxes, insurance, maintenance reserves, dock management, road association contributions, and periodic capital expenditures can add $20,000 to $40,000 or more per year on a property in the $1.5 million range.
- Ignoring zoning restrictions: Not every Muskoka or Haliburton property allows short-term rentals, new structures, or significant alterations. Zoning designations, permitted uses, and shoreline setback requirements should all be confirmed with the relevant municipality before the offer is made.
- Choosing emotional over practical fit: A cottage that looks beautiful in August can present significant challenges in shoulder season if road access is limited, maintenance demands are high, or the well or septic systems cannot support the way you want to use the property.
- Skipping the title review: Waterfront titles frequently carry easements for hydro lines, rights of way for neighbouring properties, or historic access agreements that significantly affect how you use the land. A thorough title search conducted by a real estate lawyer experienced in waterfront transactions is not optional.
- Overlooking capital gains implications: Unlike a principal residence, a cottage is subject to capital gains tax when sold. Buyers who intend to hold the property long-term or pass it to family members should engage a qualified tax advisor before closing.
For authoritative guidance on recreational property regulation in Ontario, the Ontario Land Registry Office provides access to title and property records relevant to your purchase.
Begin Your First Cottage Search With Confidence
The right cottage in Ontario is waiting. With the right preparation, honest guidance, and an advisor who understands this market deeply, the process of becoming a first-time cottage buyer in Ontario does not have to be overwhelming. CV Real Estate is here to support you from your first question through to closing day. Book a buying call to start a conversation with a cottage property specialist who knows Ontario’s recreational markets from the inside.
Frequently Asked Questions
1. Can a first-time homebuyer apply the Land Transfer Tax rebate to a cottage purchase?
No. Ontario’s first-time homebuyer Land Transfer Tax rebate applies specifically to a principal residence. A recreational property purchase does not qualify, even if it is your first property transaction in Ontario. The rebate program is designed to assist buyers purchasing a home they will occupy as their primary dwelling, which a cottage does not satisfy by definition. Our guide to first-time cottage buyers covers what does and doesn’t apply when buying a recreational property.
2. How much do I need for a down payment on an Ontario cottage?
Most lenders require a minimum of 20% for a recreational property mortgage. Properties classified as seasonal or with limited road access may require 25% to 35%. CMHC mortgage insurance is not available for recreational properties. Our guide to cottage mortgage options covers the full range of financing scenarios buyers encounter.
3. What inspections should a first-time cottage buyer commission?
A thorough cottage inspection includes a general building inspection, a septic system assessment by a licensed inspector, well water quality testing for bacteria, nitrates, and hardness, and a structural review of any docks or water-adjacent structures. Buyers should budget $1,500 to $3,000 or more for a complete assessment. Our cottage inspection guide walks through what each of these assessments covers.
4. Can I rent out my Ontario cottage as a short-term rental?
This depends on the zoning designation of the property and the regulations of the local municipality. Some Ontario municipalities have introduced licensing requirements or restrictions on short-term rental activity. Review our guide to STR rules in Muskoka and confirm local bylaws before relying on rental income in your financial plan.
5. How long does it take to close on a cottage in Ontario?
A typical cottage purchase in Ontario takes 30 to 90 days from accepted offer to closing, depending on the complexity of the transaction, the time required for due diligence, and financing arrangements. Transactions with well, septic, and permit reviews tend to require a longer condition period than standard residential purchases. Our cottage closing costs outlines what to expect during this period.
6. Is it worth working with a real estate agent who specializes in cottage properties?
Yes, without qualification. Recreational property transactions involve specific knowledge around waterfront law, shoreline regulations, septic systems, Crown land classifications, and local market pricing that generalist agents may not possess. A specialist advisor reduces your risk and improves the likelihood of a smooth, well-informed transaction. Our guide on questions to ask a cottage real estate agent can help you get the right fit.
Key Takeaways
- Working with a specialist advisor who understands waterfront law, local market data, and STR regulatory complexity is one of the most effective risk-mitigation strategies available to a first-time cottage buyer.
- Recreational property financing in Ontario follows stricter rules than principal residence mortgages, including a minimum 20% down payment and no CMHC mortgage insurance eligibility.
- First-time cottage buyers should build a full budget before viewing properties, including Land Transfer Tax, legal fees, inspection costs, insurance, property taxes, and ongoing maintenance reserves.
- Ontario cottage regions vary significantly in character, pricing, regulatory environment, and short-term rental eligibility. Selecting the right region for your lifestyle and budget is a critical early decision.
- Waiving conditions on a cottage purchase carries substantially more risk than on a standard residential transaction, given the volume of latent defects that only thorough due diligence can uncover.
Meet The Team
We’re cottage country enthusiasts and vacation property experts, helping renters, buyers, and sellers reach their goals for more than 20 years.